How Private Jet Charter Operators Make Money | BizJet Journal
Market & Finance · analysis
How Private Jet Charter Operators Make Money: Revenue, Utilization and Cost
Follow charter revenue through paid hours, positioning and operating costs. A transparent aircraft model shows why busy jets can still produce weak returns.
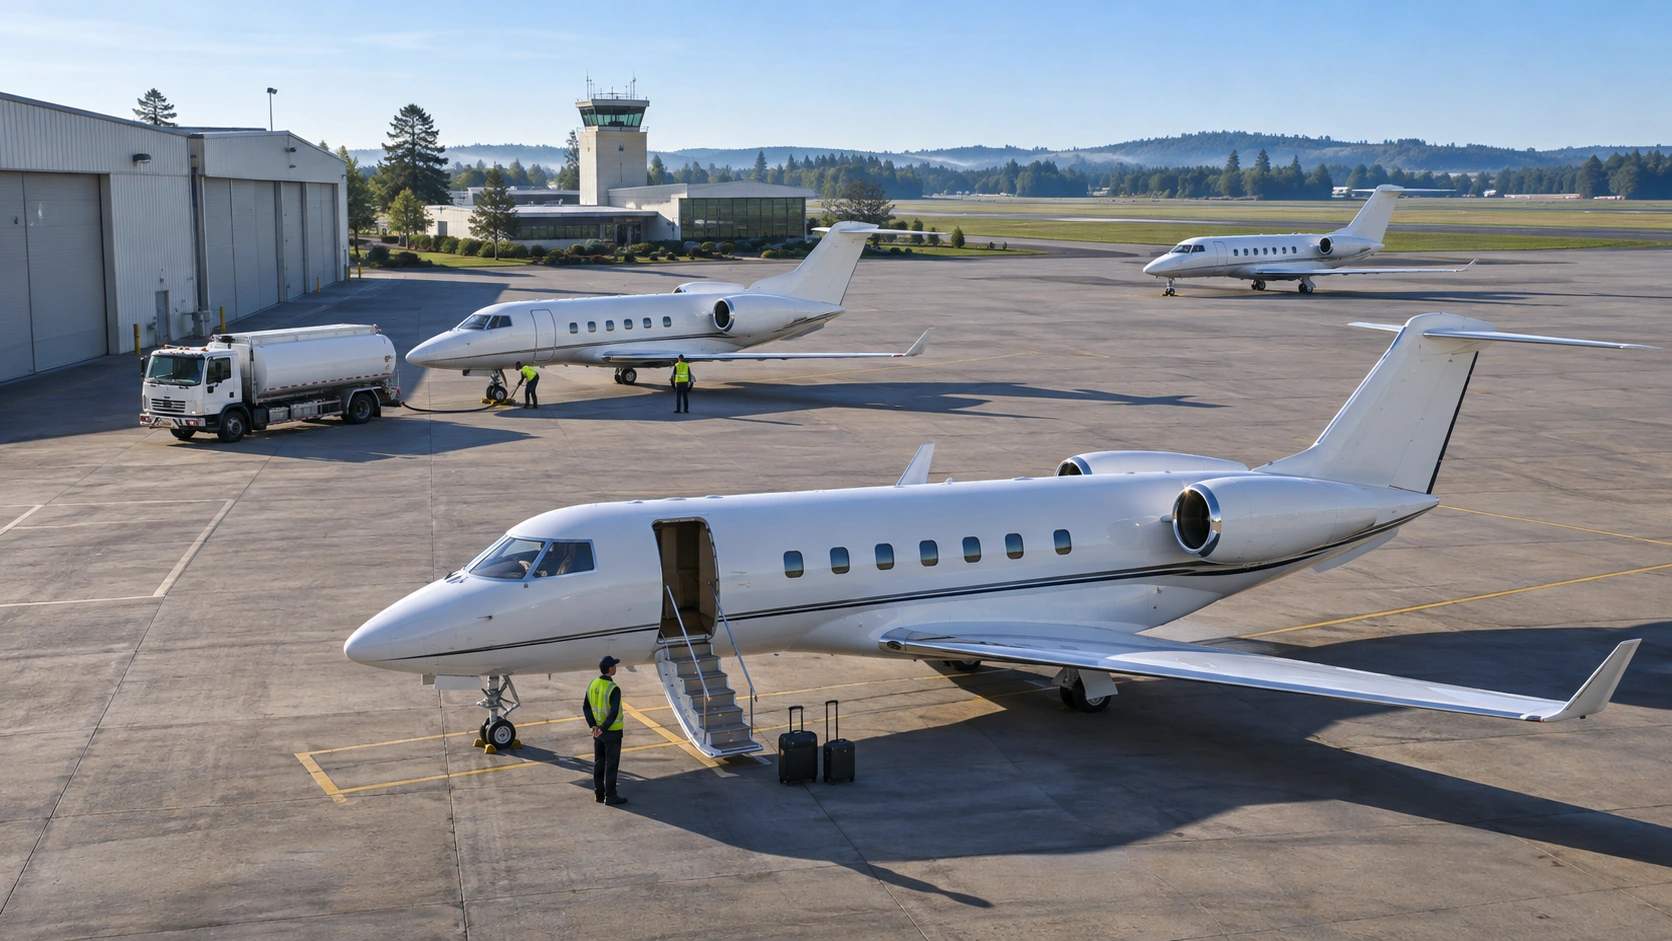
Business jets preparing for flights on an airport apron. BizJet Journal Illustration
A charter jet can look busy and still lose money. What matters is how much revenue its flying produces after repositioning, trip expenses and the cost of keeping the operation ready. Ten hours with passengers and five empty hours have very different economics from ten passenger hours and one empty hour, even if customers pay the same rate.
To understand how private jet charter operators make money, follow one aircraft's contribution before moving to the whole company. Separate the hours customers pay for from the hours the aircraft flies, then identify costs that continue while it sits on the ground.
Identify what the operator actually sells
An operator can sell flights directly to travelers or provide wholesale flying to brokers and other aviation businesses. A membership may add recurring fees and contractual access obligations. An aircraft-management agreement can add management fees, with expenses and charter proceeds allocated under the owner's contract.
The ownership model changes the calculation. An operator-owned jet ties up capital and creates depreciation and financing exposure. A leased aircraft adds lease commitments. An owner-managed jet requires you to understand the owner's share of revenue and which party pays each expense. The customer invoice alone does not reveal what the operator keeps.
As a real-world reference, flyExclusive's 2025 annual report describes retail, wholesale, club and fractional flight revenue alongside maintenance services. It illustrates why the revenue of a diversified aviation company cannot be assumed to come entirely from ordinary charter trips.
For any analysis, draw the money flow from the traveler to the selling company, the actual operator and, where relevant, the aircraft owner. The distinctions in private jet broker versus aircraft operator explain why those entities may differ. A broker's retained transaction margin and an operator's aircraft contribution are different economic measures.
Follow maintenance delays from the hangar to usable fleet supply, with a downtime model and a clear distinction between current support capacity and future projects.
A jet sold below its purchase price can still create taxable gain. Separate US sale recapture, loan payoff cash and business-use recapture with worked examples.
Start with explicit definitions. In the model below, a paid hour is one hour generating the assumed charter revenue. A flown hour is an hour the aircraft actually flies, including unpaid positioning. For simplicity, paid hours equal occupied flight hours; there are no billing minimums, taxi-time adjustments or separate positioning charges.
Actual contracts can differ. A short flight billed at a minimum duration produces more invoice hours than flight hours. A customer may pay a trip price that includes positioning, even though the positioning segment carries no passengers. You cannot interpret a paid-hour percentage until you know which convention is being used.
Take an example of a flight requiring three passenger hours and two positioning hours. At an illustrative $7,500 per paid hour, revenue is $22,500. At $3,000 variable cost for each of the five flown hours, variable costs are $15,000, leaving $7,500 before fixed costs.
If another compatible trip eliminates one positioning hour, the same customer revenue leaves $10,500 before fixed costs. The improvement is $3,000 without raising the passenger's price. This is why network fit matters and helps explain why one-way charter pricing does not simply equal half a round trip.
Track aircraft availability as well. A fleet may have strong demand but insufficient serviceable aircraft or crews to fulfill it. flyExclusive defines its total flight hours using actual airborne time and discusses downtime when explaining hours per aircraft. That is another reason not to compare an invoice-hour metric directly with an airborne-hour metric.
Build the cost structure from the aircraft upward
Use two cost layers. The first captures costs associated with flying: fuel, maintenance consumption or program charges, airport handling, landing charges and trip-related crew expenses. Some respond to flight hours, others to cycles, destinations or overnight stays. A single hourly assumption is a modeling convenience, not a description of every invoice.
The second layer covers readiness and organizational costs: salaries, training, insurance, hangar commitments and the allocated expense of scheduling, management and administration. These costs do not disappear when this week's booking cancels. They may still change in steps as the business adds aircraft, personnel or facilities.
For the following illustration, assume an operator-owned aircraft with 1,000 total annual flown hours, a $3,000 blended variable cost per flown hour and $1.8 million in fixed costs and allocated overhead. Lease payments and owner revenue distributions are absent because of the assumed ownership structure. Depreciation, financing and tax sit outside the modeled result.
Maintenance needs careful treatment. A budgeting reserve for a future inspection is not necessarily the accounting expense recognized that month. Nor should a model count the same maintenance twice by including a full hourly allowance and then treating the entire covered inspection invoice as an additional economic cost. Reconcile the cost model to actual program payments, uncovered work and the accounting policy.
The model is deliberately transparent so you can replace each assumption. Fuel price, stage length and maintenance status could make $3,000 an unsuitable input for a particular aircraft. The arithmetic demonstrates the business mechanism; it does not estimate a named operator's margins.
Find the utilization needed to cover fixed costs
Assume 700 of the 1,000 flown hours are paid at $7,500 each. No membership revenue, taxes collected for governments or separately reimbursed extras are included.
Annual aircraft model
Calculation
Result
Flight revenue
700 paid hours × $7,500
$5,250,000
Variable operating costs
1,000 flown hours × $3,000
−$3,000,000
Contribution after variable costs
Revenue less variable costs
$2,250,000
Fixed costs and allocated overhead
Assumed annual amount
−$1,800,000
Surplus before depreciation, financing and tax
Contribution less fixed costs
$450,000
The $450,000 is 8.57% of revenue, but it is not net profit. The aircraft still needs to support the excluded capital-related costs before producing a final return to its owner.
Holding total flown hours and all cost assumptions constant, break-even paid hours are:
That is a 64% paid-hour share of 1,000 flown hours under this model's definitions.
Paid hours within 1,000 flown hours
Paid-hour share
Revenue
Surplus before excluded costs
600
60%
$4,500,000
−$300,000
640
64%
$4,800,000
$0
650
65%
$4,875,000
$75,000
700
70%
$5,250,000
$450,000
750
75%
$5,625,000
$825,000
800
80%
$6,000,000
$1,200,000
Changing 50 hours from unpaid to paid at the same total flying adds $375,000 of revenue and modeled surplus. Conversely, a 10% increase in the variable-cost assumption adds $300,000 of annual cost, reducing the base-case surplus to $150,000. A 5% reduction in the paid-hour rate reduces revenue by $262,500 and leaves $187,500.
These sensitivities show how a seemingly comfortable operation can become thinly profitable. They also separate two strategies: sell a greater proportion of existing flying, or add more total flying. The second strategy adds operating costs as well as revenue.
Total flown hours and modeled costs are held constant. Paid hours are assumed to equal occupied flight hours, with no invoice minimums or separate positioning charges. · BizJet Journal
Read reported margins with their definitions attached
Aircraft contribution, company gross profit and final earnings answer different questions. An aircraft-level model may omit central expenses. A company's adjusted metric may exclude depreciation, compensation or restructuring items that remain relevant to the total investment outcome.
Wheels Up's 2025 annual report reconciles its adjusted contribution measure to GAAP gross profit. It also explains gross and net revenue presentation when acting as principal or agent. These disclosures matter more to a comparison than the percentage printed beside a margin label.
Consider an independent illustration: a company collects $25,000 and pays another provider $22,000, retaining $3,000 before its own overhead. If the applicable accounting requires gross presentation, those amounts appear as $25,000 revenue and $22,000 cost. Under net presentation, revenue may be the $3,000 retained amount. The same retained dollars do not imply comparable revenue-based margins.
Customer prepayments need their own reconciliation. Receiving $1 million for future flights improves today's cash balance, but the company still owes transportation. Wheels Up reports prepaid flights within deferred revenue. Spending that cash does not eliminate the future operating costs required to fulfill the customer obligation.
Understand the limits of flying more
An extra trip is attractive when its incremental revenue exceeds its incremental costs and it does not displace a better use of scarce capacity. The annual average alone cannot settle that decision.
Suppose an additional two-hour passenger trip sells for $12,000 and requires one extra positioning hour. At the model's $3,000 variable cost, its three flown hours consume $9,000, leaving $3,000 before any additional fixed or exceptional costs. If a fourth flown hour becomes necessary, that contribution disappears under the same assumptions.
A discounted flight can therefore help during a quiet period yet be unattractive on a peak day. The operator must also consider where the aircraft ends, what the crew can legally and practically operate next, and whether additional use brings maintenance forward. A trip that prevents a higher-contribution booking tomorrow has a cost beyond today's fuel invoice.
The useful operating dashboard connects paid hours, total hours, achieved rates, incremental costs and availability. More flights improve the business only when those flights add enough contribution to support the capacity they consume.
Frequently asked questions
Can a high charter rate coexist with an operating loss?
Yes. A high rate on a small number of paid hours may not cover repositioning and fixed costs. In the illustration, 600 paid hours at $7,500 generate $4.5 million, but the modeled cost base is $4.8 million before depreciation, financing and tax.
Are empty-leg sales always profitable?
No. A sale can improve an already-required positioning flight, but passenger handling, itinerary changes and added flying can create additional costs. The operator must also consider commitments to the original trip and the aircraft's next assignment. Compare the incremental revenue with the full change in costs and scheduling options.
Why are customer deposits different from earned revenue?
A prepayment for future flying provides cash before the service is delivered. The operator must retain the ability to fulfill that obligation and recognize revenue according to the applicable contract and accounting policy. Cash received today is not proof that the associated flights will be profitable.
Tags
Understand aircraft orders, backlog and book-to-bill ratios, including firm commitments, cancellations, unit versus value measures and delivery visibility.