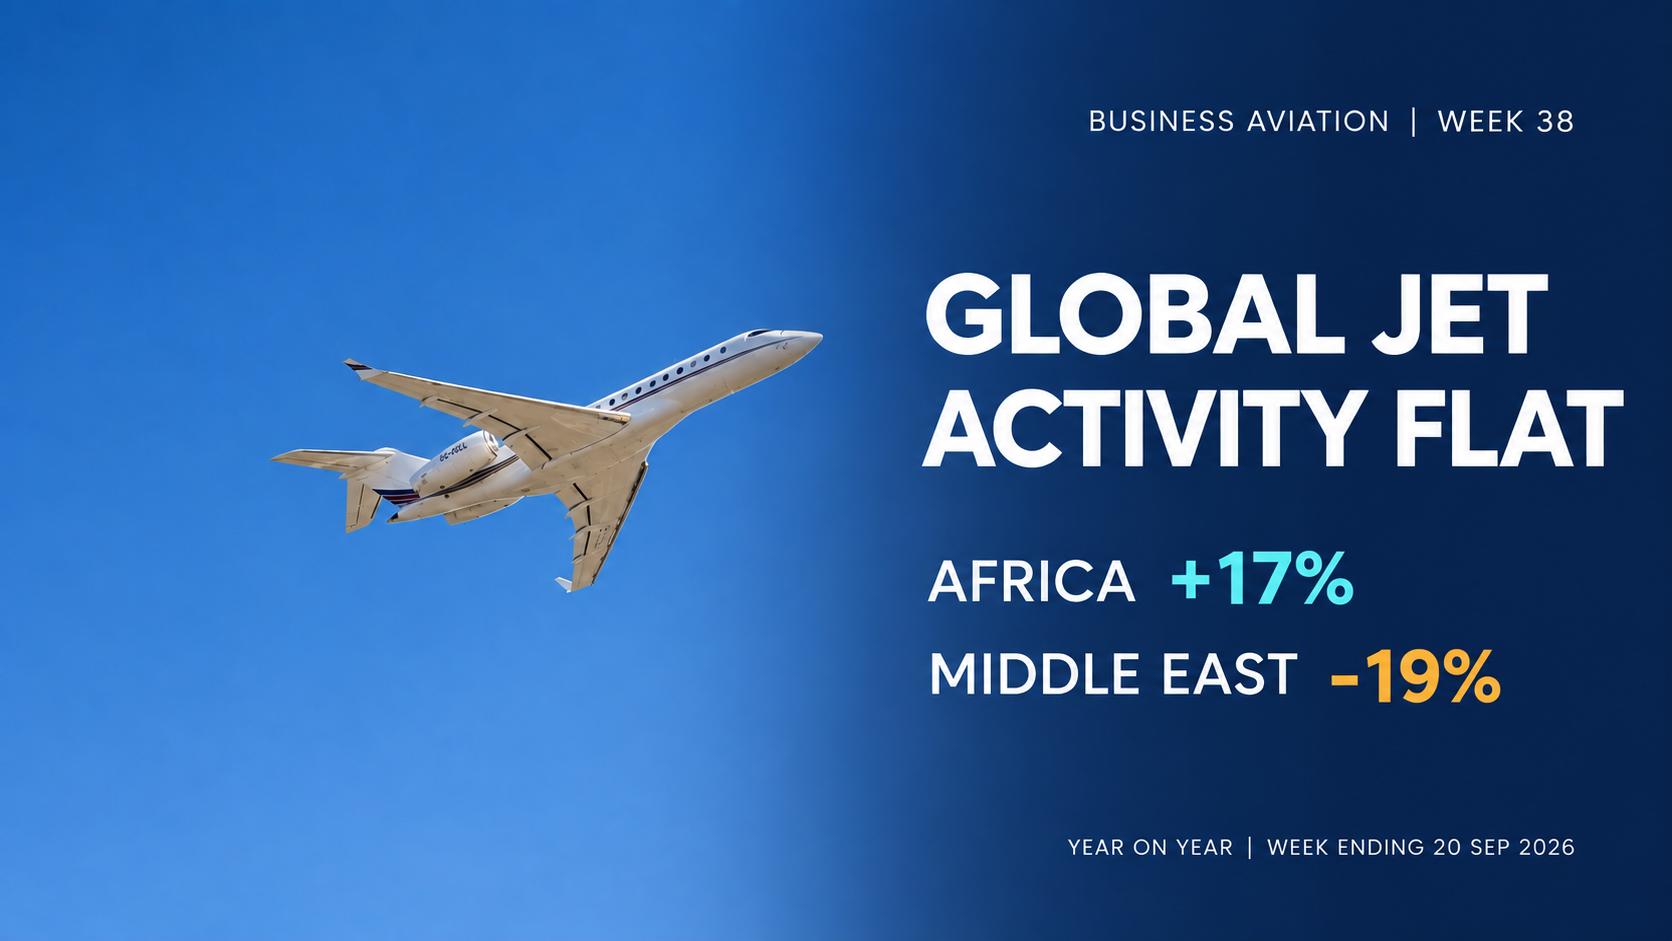
Global private jet activity was flat compared with a year earlier for the second consecutive week, but the worldwide figure masks a sharp regional divide.
WINGX recorded 81,090 departures in the week ending 20 September 2026. That was about 1% more than the previous week, while year-to-date activity remained 3.3% ahead of 2025. The dataset includes business jets and VIP airliners.
Africa grows while the Middle East contracts
Africa recorded 939 departures, up 17% from the same week last year. The Middle East recorded 1,290, down 19%. North America rose 1%, while Europe was flat; within Europe, Germany was down 7%. These figures point to different market conditions, not a uniform change in global demand.
Africa’s weekly total is also much smaller than North America’s, so a strong percentage gain should be tested against several weeks of activity before it is treated as a lasting trend.
The split extends to operating models. WINGX counted 30,890 U.S. charter and fractional departures, up 1% year over year, while the comparable global category was down 1%. Departure counts measure flying activity; they do not establish what customers paid or whether operator margins improved.
An opportunity that needs more evidence
Africa’s result arrives alongside an African Business Aviation Association study described by Aviation Week on 22 September. Its preliminary findings identify potential demand for midsize jets, limited charter access and a need for more support infrastructure. The full research is still pending.
For manufacturers, operators and service providers, the useful question is where sustained flying demand meets a shortage of suitable aircraft, maintenance or ground services. The next WINGX readings will help show whether Africa’s recent increase persists and whether the global plateau continues. For now, the clearest conclusion is that business aviation demand needs to be read by region and operating model, not by one worldwide headline.